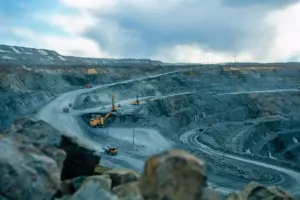
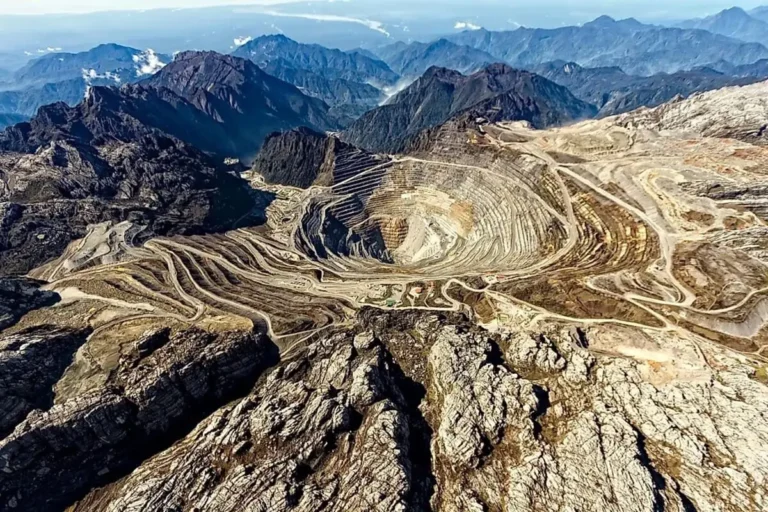
The mining industry is facing growing operational complexity: deposits are aging, ore grades are falling, and new projects demand increasingly difficult technologies. In EY’s 2027 risk ranking, operational complexity took first place, ahead of capital availability, supply disruptions, rising costs, and geopolitics. The findings are based on a survey of 400 industry executives.
According to Paul Mitchell, EY’s global mining and metals leader, complexity has always been part of mining, but now it is growing: mines are aging, reserves are being depleted, and new deposits are harder to develop and process.
The biggest contributor to operational complexity is permitting delays, followed by instability in ore grades, cited by 29% of respondents. Labor availability, materials handling, processing capacity, transport, and equipment reliability affected 24–26% of those surveyed. As mines age, operators have less room to maneuver: it is harder to change schedules, blend ore, and redirect flows, so disruptions are costlier.
Capital availability ranked second. The money is there, but investors are becoming more selective because of diverging commodity prices. In search of funding, 44% of companies are turning to equipment manufacturers, and 39% each to sovereign funds and government investment.
Supply disruptions ranked third as a risk: they hit the delivery of materials, the operation of processing, and access to markets. To reduce vulnerability, 53% of companies are investing in supply chain traceability technology, and 52% are building up inventories. Rising costs are not offset even by high commodity prices, and productivity initiatives often founder on organizational fragmentation.
Governments are stepping up their role: critical minerals financing grew more than fourfold from 2023 to 2025, to roughly $65 billion. 28% of executives each expect direct government investment in the coming year. Geopolitics ranked fifth but influences capital allocation, supply chains, and site selection.
A separate new risk is cybersecurity. According to EY, 67% of mining and metals assets sit in a vulnerability zone with insufficient visibility and weak protection.
For producers of critical raw materials, the gap is widening between governments’ ambitions and the industry’s real capabilities. Mitchell advises not waiting for uncertainty to disappear, but revisiting assumptions, portfolios, and capital decisions, building more flexibility into operations.
Source: EY